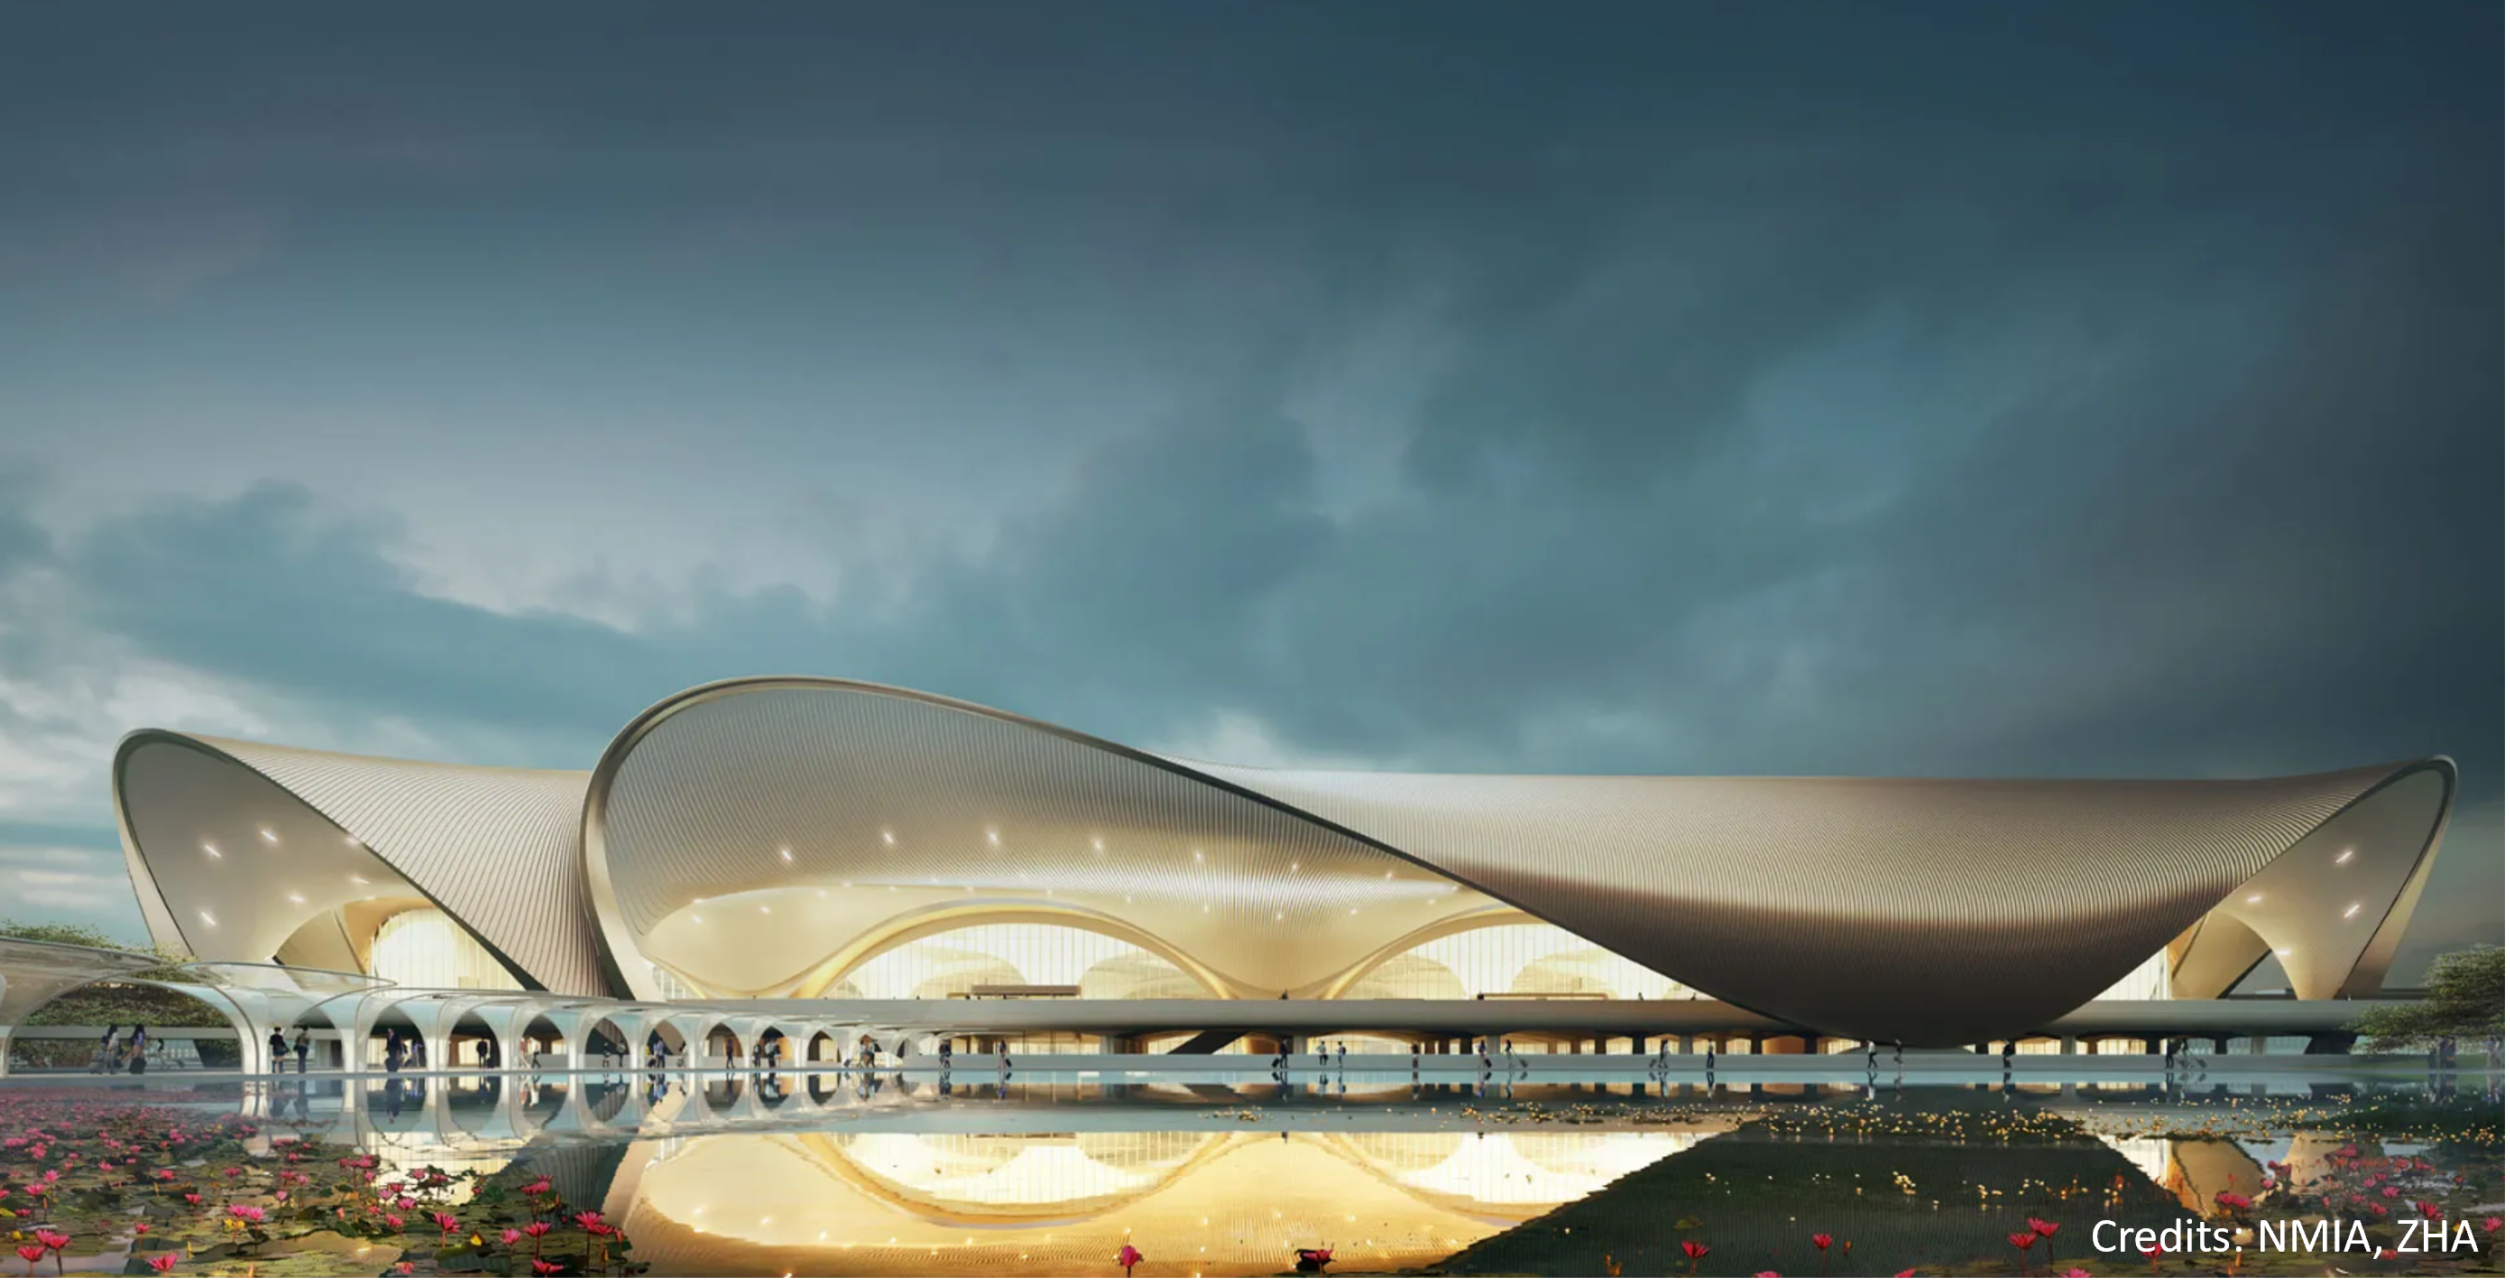
Navi Mumbai is open. Now comes the harder part: deciding which flights go where. We looked at seventeen years of monthly traffic and the full Summer 2026 schedule at BOM. The conclusion is uncomfortable. NMI has added capacity. It has not added much traffic. Terminal 1 comes down in April 2027, which leaves the airport system less than six months to get the allocation right.
A Capped Airport, Not a Slowing Market
BOM's growth curve shows a capacity problem, not a demand problem. Traffic doubled from 24.8 million in 2009 to 49.9 million in 2018, compounding at 6.6% a year through 2019. Then it hit the ceiling. Growth fell to 2.8% a year between 2019 and 2025, and throughput has held at about 55 million since the recovery: 54.8 million in 2024, 55.5 million in 2025. Demand didn't shrink. Airfield capacity was the bottleneck.
Scarce slots went to the highest-yield routes. International grew at 3.5% a year from 2019 to 2025, against 2.5% for domestic, and its share of BOM traffic rose from 28.2% to 29.4%. The flip side: BOM's domestic network has had almost no room to grow for six years. That held-back domestic demand is exactly what NMI was built to capture.
Summer 2026: Running at the Limit
The Summer 2026 schedule (1 April to 31 October) left no much room to grow further. 196,276 passenger movements over 214 days. That is 917 a day and about 182,000 seats. The daily range is 896 to 948, so there is no off-peak day. Every hour from 04:00 to midnight runs 35 to 50 movements, peaking at about 51 at 11:00. The only quiet hour is 03:00. No spare capacity, at any time of day.
Two carriers own most of it. IndiGo runs 401 movements a day, 43.7% of the total, and holds 54.7% of domestic seats. The Air India group (Air India plus Air India Express) runs about 301, or 32.8%. Akasa has 6.8%, SpiceJet 2.7%. International is 27.1% of movements and 31.1% of seats. About 870 international departures a week were filed. The six Gulf states take about 46% of them, led by the UAE (194) and Saudi Arabia (88). MIAL's current figure of 770 reflects the Gulf cuts since the February filing.
Navi Mumbai's First Year: Redistribution, Not Growth
NMI opened in late December 2025 and has handled 3.3 million passengers so far (till September 2026), almost all domestic. Its share of regional domestic traffic went from 5.3% in January to a peak of 16.1% in May (635,000 passengers). Look at BOM to see where those passengers came from. Between April and September 2026, BOM domestic fell 9.5% year on year, from 19.1 million to 17.3 million. NMI added 2.7 million. Regional domestic grew 4.6%. With BOM international also down 4.9% on the Gulf disruption, total system traffic grew just 1.9%, from 27.0 million to 27.5 million. July, August and September were all negative year on year.
NMI's share has also slipped. After May it fell every month, to 10.7% in September (331,000 passengers). The monsoon explains some of it. Not all. Some passengers, and some airline capacity, have gone back to BOM. International at NMI has barely started: about 6,300 passengers since July, against roughly 16 million a year at BOM. Over the last twelve months the system handled 56.4 million passengers, 53.1 million at BOM and 3.3 million at NMI. So far, the second airport has mostly given existing Mumbai passengers a second place to fly from.
Terminal 1: The 20 Million Passenger Question
The T1 rebuild makes sense long term. Capacity goes from 15 to 20 million passengers a year, and contact stands from 7 to 25. The problem is phasing. Demolition starts April 2027. A new North-West Pier at T2 (January 2027 to March 2029) partly offsets the loss. The new T1 arrives in December 2030. On MIAL's own numbers, regional capacity bottoms out at 60 million passengers a year in October 2027 before climbing to 85 million. Against 56.4 million today, plus any growth, that is almost no headroom for 2027–28.
The schedule shows exactly what gets displaced. T1 is fully domestic and serves three airlines. It handles 215 movements a day, 23.5% of BOM. That is 16.0 million annualised seats, or about 13.6 million passengers at an 85% load factor, in line with its 15 million nameplate. IndiGo has 146 of those daily movements (9.8 million passengers), Akasa 49 (2.9 million) and SpiceJet 21 (0.9 million). Exposure varies sharply. T1 is 36% of IndiGo's BOM operation, 79% of Akasa's and 84% of SpiceJet's. It is an all-narrowbody operation serving 43 destinations, led by Bengaluru (17.5 daily departures), Chennai, Hyderabad, Kolkata and Delhi.
T2 cannot take this traffic. It was scheduled for about 49.5 million annualised seats in Summer 2026, roughly 42 million passengers, which is above design capacity. Once T1 closes, BOM's constraint moves from the runway to the terminal. The runway slots freed by T1's 215 daily movements are worth nothing without terminal space to use them.
MIAL's answer is to move about 265 of 770 weekly international departures, around 5 million passengers a year, to NMI from Summer 2027. That frees T2 space for displaced domestic flights. IndiGo, Air India and Akasa have reportedly agreed to about 3 million passengers' worth. Foreign carriers object to what they call a unilateral slot cut. The arithmetic is simple. If 5 million international passengers leave T2, T2 can take about 5 million of T1's 13.6 million. The other 8–9 million domestic passengers go to NMI or are lost. If only the agreed 3 million moves, the overflow rises to 10–11 million. Either way, NMI goes from 3.3 million passengers today to around 17 million by Summer 2027–FY28. That is close to its 20 million Phase 1 capacity, well before Phase 2 (50 million by 2030) arrives.
The Alliance Lens: Allocate Networks, Not Airlines
BOM's international market runs on networks, not individual airlines. By Summer 2026 international seats: low-cost carriers 40.0% (IndiGo alone 27.6%), Star Alliance 26.3%, unaligned full-service carriers 16.6% (mostly Gulf hubs, led by Emirates at 6.5% and Etihad at 3.5%), oneworld 9.2% and SkyTeam 7.9%. By weekly international departures that is roughly 396 low-cost, 214 Star, 127 unaligned, 76 oneworld and 56 SkyTeam.
Star is the backbone. Air India alone has 13.9% of international seats and 133 weekly departures, alongside Singapore Airlines, Lufthansa, Ethiopian, Thai, Turkish, Swiss, ANA and EgyptAir. Air India's domestic network also gives Star 30.0% of BOM's domestic seats, or 28.8% of all seats at the airport. It is the only alliance with its own domestic feed in Mumbai. Split Star across two airports and the domestic-to-international transfers behind those long-haul frequencies break. No realistic minimum connecting time covers a cross-harbour road transfer.
Oneworld (British Airways, Qatar Airways, Cathay Pacific, Malaysia Airlines, SriLankan, Oman Air, Royal Jordanian) and SkyTeam (Virgin Atlantic, Saudia, Air France, KLM, Vietnam Airlines, Kenya Airways, SAS) have no Indian member. Their India connections depend on codeshares, above all IndiGo's partnerships with carriers such as Air France-KLM, Delta, Virgin Atlantic and Qatar Airways. Obviously, their allocation has to follow IndiGo's. It cannot be decided separately.
This changes how the 265 should be found. A flat one-third shift per carrier takes a third of Star, a third of oneworld and a third of SkyTeam out of BOM. Every network splits at once. An alliance-based shift gets to almost the same number and breaks nothing. Foreign low-cost carriers (about 62 weekly departures) plus the international flights of Akasa, Air India Express and SpiceJet (about 74) make 136. Add IndiGo's point-to-point Gulf services (121 of its 260 weekly international departures) and you are at about 257. Star, Oneworld, SkyTeam and the Gulf hubs stay intact at T2, along with the IndiGo flights that connect with partners. Air India Express sits inside the Air India group, but its Gulf flights are largely point-to-point, so moving them does not break Star connections.
Avinia's View: Allocate by Network, Catchment and Product
Asking every airline to move a third of its flights is simple to administer and bad for both airports. Splitting a Mumbai operation evenly breaks connecting banks, doubles overheads and confuses passengers. The allocation should follow four principles.
First, move whole carriers where exposure is already high. Akasa (79% of its BOM movements at T1) and SpiceJet (84%) have to relocate most of their operations anyway. Move them to NMI as complete bases: about 70 daily movements and 3.8 million passengers. NMI gets two operators with full networks, not token frequencies. The airlines get one coherent Mumbai operation instead of two half-operations.
Second, split IndiGo by network role, not by percentage. Its 146 daily T1 movements will make or break the transition. Trunk routes such as Bengaluru, Delhi, Hyderabad and Chennai can support high frequencies at both airports, so passengers choose by where they live. Connecting banks and international feed stay together at BOM. Point-to-point leisure and tier-2 routes go to NMI.
Third, allocate international traffic by alliance, not by carrier. One alliance, one airport. The same goes for each codeshare partnership. Star stays together at BOM around Air India's hub. Oneworld and SkyTeam stay with the IndiGo flights that feed them. What moves should be point-to-point: low-cost and narrowbody Gulf services with no alliance connections to protect. Forcing foreign alliance carriers out invites bilateral and legal friction. A clear alliance-based rule, backed by incentives, will go further than a flat mandate.
Fourth, define catchment zones and price them. The MMR is not one catchment. Navi Mumbai, Thane, Kalyan-Dombivli, Panvel, Raigad and the Pune corridor lean to NMI. The central suburbs are contestable, and the Atal Setu has made South Mumbai contestable too. Airlines should plan around these zones, and charges should back them up. IndiGo's call for lower per-passenger charges at BOM once T1 is rebuilt shows tariffs will drive this transition. With both airports under Adani, the region has a rare opportunity: set differential aeronautical charges across the system to maximise total traffic, not to protect each airport's revenue.
Conclusion: Make NMI a Choice, Not an Overflow
The demand is real. BOM sat at its ceiling for six years, and the region still handled 56.4 million passengers in the last twelve months. But NMI's first year shows that capacity without an allocation strategy mostly moves passengers around. T1 takes 13.6 million passengers' worth of capacity out from April 2027, and regional capacity drops to 60 million in October 2027. The region cannot afford a second airport that passengers see as the overflow option.
The airports, airlines should treat Summer 2027 as a once-in-a-generation network redesign, not a temporary inconvenience. Move whole carriers and whole flight banks. Keep each alliance together. Steer point-to-point demand by catchment. Back it with system-level pricing. Get this right and Mumbai comes out of the T1 rebuild in 2030 with two complementary airports and about 85 million passengers of capacity. Get it wrong and it has two airports competing for the same passengers.
Source: Avinia Labs analysis of BOM/NMI monthly traffic (2009–Sep 2026) and the BOM Summer 2026 filed schedule by Cirium